Regulation matures: what the new instalment frameworks mean for shoppers
Licensing, affordability checks, and fee caps are becoming formal requirements across the region. MiSPay explains what changes for shoppers and merchants, and what should have been standard all along.
Instalment payments are moving from a lightly supervised product to a licensed one across the region, and MiSPay supports the direction of travel without qualification.
Formal frameworks now cover licensing, affordability assessment, fee disclosure, credit reporting, and complaint handling. For a company that already operates under licence in all three of its markets, most of the requirements are documentation of existing practice. Some are genuine change, and those are worth stating plainly.
What the frameworks require
Licensing. Providers must be authorised before offering instalment credit
Affordability. A documented assessment for every plan, not just onboarding
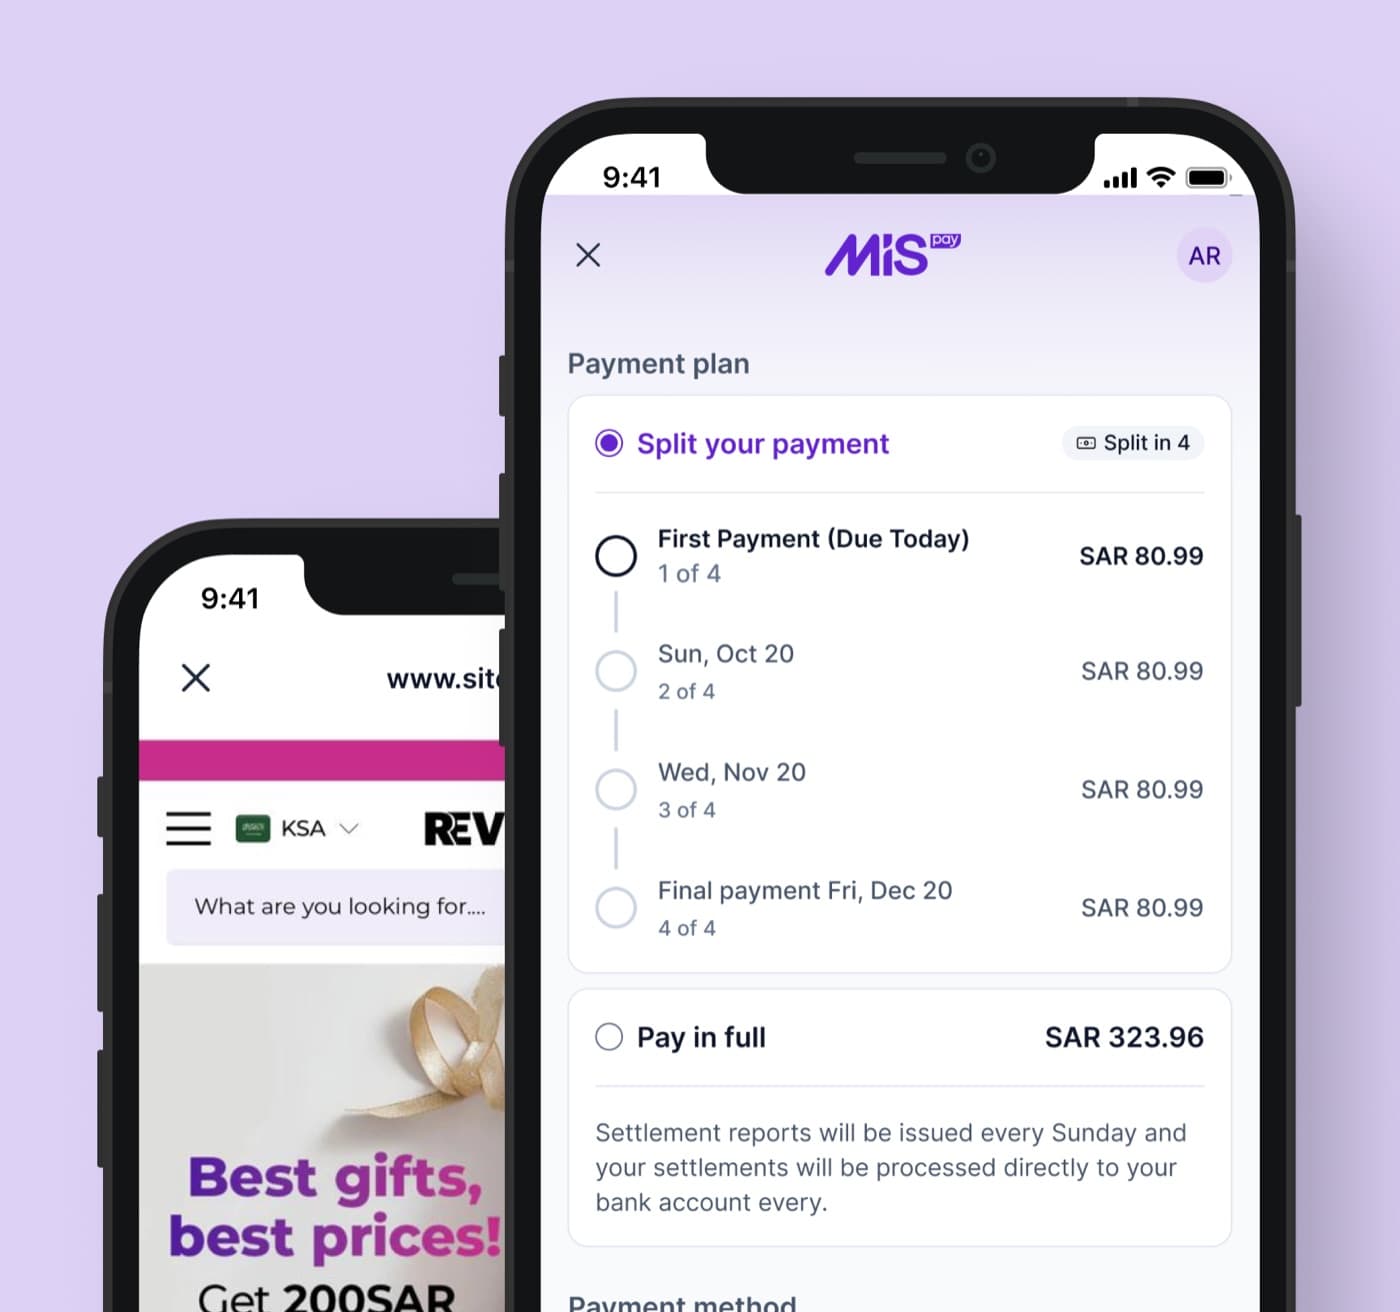
Disclosure. Total cost, fees, and due dates shown before confirmation
Reporting. Plan data shared with credit bureaux under defined rules
Complaints. A defined path, defined timelines, and an escalation route
What actually changes
Credit reporting
The most consequential change. Where instalment plans are reported to bureaux, responsible repayment starts to build a record — and missed payments carry weight they previously did not. Shoppers should treat an instalment plan as credit, because it now is on the record.
Affordability documentation
Assessments must be evidenced, not just performed. This raises the bar for providers who relied on thin signals and light-touch checks.
Fee structures
Caps on late fees, and prohibition of fees applied to fees, remove the worst edge cases in the market. MiSPay has never compounded fees, and welcomes the floor being raised for everyone.
"Good regulation does not slow a well-run provider down. It removes the providers whose economics depended on the customer's worst month."
What MiSPay is doing
Publishing plan terms in plain Arabic and English on every confirmation screen
Extending affordability documentation retention to meet the longest applicable requirement
Adding an in-app view of what is reported to bureaux and when
Committing to a 48-hour first response on every formal complaint
Publishing an annual responsible-lending report with approval and late-payment data
What merchants should prepare
Merchants do not carry the licensing obligation, but disclosure at the point of sale matters. Product pages, in-store signage, and staff scripts should state plan terms accurately, and returns policies should describe what happens to an active plan. MiSPay is providing updated merchant messaging templates in both languages, and the merchant console now flags pages where plan messaging is missing.
About MiSPay
MiSPay is a regional payments company that lets shoppers split purchases into predictable instalments and helps merchants convert more of the demand they already have.
For press enquiries, contact press@mispay.co.
Writing about MiSPay?
Our press team can help with data, quotes and brand assets. We usually reply the same day.